
Key takeaways
• The US faces a critical juncture for retirement policy evolution as Social Security's retirement trust fund is projected to run dry in late 2032, triggering a roughly 22% benefit cut.
• It’s not just the US: retirement systems everywhere face the same four pressures: aging populations, AI reshaping early careers, wealth inequality, and political volatility.
• South Africa's two-pot system, Australia's superannuation, and UK auto-enrolment each solve a different piece of the puzzle.
• The US can combine those lessons: auto-enrolled, out-of-plan emergency savings with a seed deposit; portable accounts with predictable retirement income; and a bigger role for employers and states.
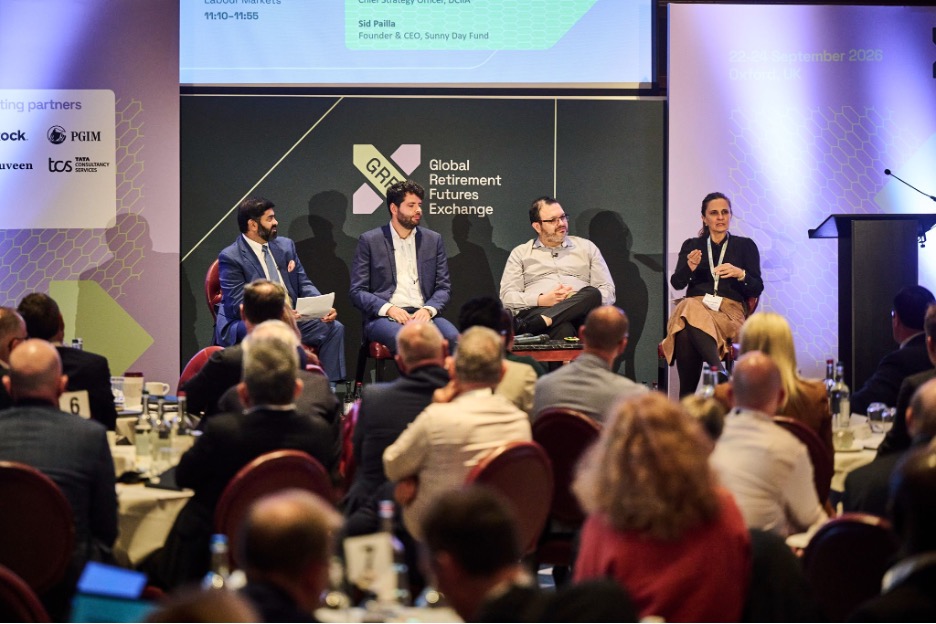
I had the unique honor of representing Sunny Day Fund, workplace emergency savings, and the US at a first-of-its-kind Global Retirement Futures Exchange. As a forever-student, I was excited to learn from the world’s systems – and the lessons were truly inspiring. My post here serves as a reflection from the event and a call-to-action for fellow stakeholders in the US who have a responsibility to deliver a retirement system where everyone can retire with dignity.
What are the three pillars of retirement policy?
Most national retirement systems are built on three pillars, a framework the World Bank popularized in the 1990s:
• Pillar 1: Public. A government-run floor, usually funded by today's workers paying for today's retirees. Social Security in the US, the State Pension in the UK, the Age Pension in Australia. Its job is to keep older people out of poverty.
• Pillar 2: Workplace. Saving tied to a job, either mandated or employer-sponsored. The 401(k), UK auto-enrolment, Australia's superannuation, Chile's AFPs.
• Pillar 3: Personal. Voluntary saving on top. IRAs, personal pensions and, for many families, the home.
The World Bank later added a "zero pillar": non-contributory support for people who never had a formal job. In much of Latin America, it's becoming the retirement plan for a large share of people.
Every country leans on the pillars differently. What struck me in Oxford is that every country is stress-testing all three at the same time, for the same reasons. And rather than thinking of these as pillars, some suggested thinking it as layers of retirement security.
What forces are reshaping retirement systems worldwide?
Four threads came up in nearly every conversation.
1. Aging is tilting demand toward the top of the age pyramid
By the late 2070s, people 65 and older are projected to outnumber children under 18 worldwide. In the US, we’re already seeing more than 11,000 people retire every single day from old age.
Fewer workers per retiree strains Pillar 1 everywhere, which puts more weight on the workplace and personal pillars. The US is no exception. In 1960, five workers paid into Social Security for every retiree. Today it's 2.9, heading toward 2.2 by the 2070s.
2. AI is rewriting the early career
A Stanford study found that 22-to-25-year-olds in the most AI-exposed occupations have seen a 13% relative decline in employment since generative AI took off. Older workers in the same jobs held steady or grew. Young graduates are also apprehensive as they now represent one in four unemployed.
Retirement systems quietly assume a career ladder: a steady job in your twenties, steady contributions, decades of compounding. If the first rungs disappear, so do the most valuable years of saving.
3. Access without savings capacity
Wealth inequality is severe almost everywhere. In the US, the bottom half of households hold 2.5% of the country's net worth, and they owe roughly four times more in consumer debt than they hold in 401(k)-type accounts. In Mexico, the bottom half has negative net wealth.
What this fundamentally means is that much of the people in most nations are so focused on their immediate financial needs that they can’t fathom an eventual retirement. We can give everyone a retirement account. But if a $400 emergency empties it, access may not be the only answer.
4. Populism is adding volatility to everything
When households are squeezed, retirement plans – often the largest asset class in most countries – become a political target. Chile let people withdraw from their pensions during the pandemic, and University of Chile researchers found it hit the poorest half hardest. Australia opened early access too.
Policies that are focused on long-term accumulation and disciplined decumulation do not hold up well in the face of penalty-free early withdrawals.
When will Social Security benefits be cut?
Unless Congress acts, Social Security's retirement trust fund is projected to be depleted in late 2032. At that point, incoming payroll taxes would cover about 78% of promised benefits. That's a cut of roughly 22% for every retiree, current and future.
That's about six years away. It's shorter than a typical car loan, and shorter than the time it takes most families to build a meaningful emergency fund.
Social Security isn't going away, but inflation is already impacting lower-income households who rely heavily on social security – so any cuts hurt. And the longer we wait, the bigger the fix gets.
That's why the four themes aren't abstract for us. Aging is shrinking the worker-to-retiree ratio. AI is pressuring the early careers that fund the system. Inequality means the households most dependent on Social Security have the least saved alongside it. And populism makes a durable bipartisan fix harder to reach.
Whatever Washington does with Pillar 1, Pillars 2 and 3 need to be ready to carry more weight for more people. Fast.
What retirement designs should the US consider?
South Africa's two-pot system: an emergency fund built into the pension
Since September 2024, South Africa's two-pot retirement system splits every contribution: one-third goes into a savings pot the worker can tap once a year. Two-thirds go into a retirement pot that stays locked until retirement.
What I find remarkable about this design is that it stops pretending. Before, many South Africans cashed out everything when they changed jobs. The new system admits that short-term needs are real, and it ring-fences the rest.
The early data is sobering. At one major administrator, 62% of this year's claims were members' third withdrawal, and most people took the full pot. I read that as a demand signal, not a failure. People need liquid savings. The question is whether that money should come out of retirement or sit next to it.
That's the question we work on every day at Sunny Day Fund. BlackRock's research found that workers with emergency savings are significantly more likely to contribute to their retirement plan. Emergency savings isn't a competitor to retirement. It's the foundation.
Australia's superannuation: mandatory and portable at scale
Superannuation ("super") requires employers to pay 12% of wages into an account the worker owns. It follows them from job to job, and since July 2026 it must be paid every payday. Australians now hold about A$4.8 trillion in super, one of the largest retirement pools in the world.
Yet the super also has some challenges:
• The self-employed and true contractors sit outside the mandate. These are some of the fastest-growing parts of the labor market.
• Contributions mirror wages. Gaps for women, carers and low earners persist, and the wealthiest fifth of households hold 61% of super by value.
• It bent under pressure. During COVID, Australians were allowed to draw on super early. Even the strongest Pillar 2 in the world doubled as an emergency fund when it had to.
The lesson: a mandate solves access and portability. It doesn't solve adequacy or liquidity.
UK auto-enrollment: making saving the default
Since 2012, UK employers have had to automatically enroll eligible workers (age 22 and up, earning over £10,000) into a workplace pension, with the right to opt out. Flipping the default worked: about 90% of eligible employees now save.
It isn't universal yet. The self-employed are outside it, and their pension saving collapsed from 48% in 1998 to 16% by 2018. A 2023 law lets the government lower the age to 18 and count contributions from the first pound earned, but no start date has been set.
The lesson is one we already know: defaults work. Now the design decision is over who counts as eligible, and what else we automate.
How can the US combine emergency savings and retirement savings?
The US has momentum of its own. State auto-IRAs now hold more than $3 billion across 1.2 million funded accounts. Trump Accounts are seeding savings at birth and has already embraced an aspect of auto-enrollment. The Saver's Match arrives in 2027. And US employers are experimenting with emergency savings as a workplace benefit in ways I didn't hear anywhere else.
Here's where I'd start:
• Unrestricted, out-of-plan emergency savings with auto-enrollment and a seed. Take South Africa's insight and put the savings pot next to the retirement plan, not inside it. Auto-enroll workers into a liquid, out-of-plan emergency savings account, seed it with a modest employer deposit without payroll taxes, and let people use it without penalties or paperwork. The retirement account stays intact for the long run.
• Portability and predictable spending to make the back half easier. Borrow Australia's "one account for life" so savings follow workers across jobs instead of leaking out at every transition. Then make retirement income as predictable as a paycheck, so people know what they can spend.
• Leverage the employer better, including through innovation and state alternatives. Employers are the most effective distribution channel we have, as the UK proved. Give them simple, low-cost ways to fund emergency savings and children's accounts. Where employers can't sponsor a plan, let state programs serve as the on-ramp, and use them to test new ideas before they scale nationally.
Why I'm hopeful about retirement policy in the US
Every system I heard about in Oxford is under pressure from the same forces at once. I don't think that's a reason for despair, I believe it's an opportunity.
When everyone is running the same experiment, we get to compare results. But with the Social Security deadline looming, now is the time to thing big – and perhaps borrow what works abroad and design for the whole life, from the emergency today to the retirement decades from now.
I’d like to thank the Aspen Institute Financial Security Program, the Defined Contribution Institutional Investment Association (DCIIA), the Center for Inclusive Money at Nest, Pensions UK, and SPARK Institute for co-hosting the first GRFX and including me and Sunny Day Fund!
Frequently asked questions
What is workplace emergency savings?
Workplace emergency savings is an employer-offered benefit that lets employees save for unexpected expenses through payroll deduction, often with employer contributions or rewards. Out-of-plan versions sit in a separate bank account, outside the 401(k).
How does South Africa's two-pot retirement system work?
Since September 2024, one-third of each retirement contribution goes to a savings pot that members can withdraw from once per tax year, and two-thirds go to a retirement pot that stays locked until retirement.
When is Social Security projected to cut benefits?
The 2026 Trustees Report projects the retirement trust fund will be depleted in late 2032, after which incoming revenue would cover about 78% of scheduled benefits unless Congress acts.
Is UK pension auto-enrolment universal?
No. It covers employees aged 22 and up who earn over £10,000, and they can opt out. The self-employed are not covered.
Why does emergency savings matter for retirement?
Without liquid savings, workers often tap retirement accounts when emergencies hit. A separate emergency fund protects long-term savings and is linked to higher retirement plan participation.